by | Oct 9, 2026 | Affordable Care Act
Yes. This one needs a more substantial rewrite than the seasonal blog. The topic can work for WCSS, but the current draft has three major problems: the audience is wrong, it misrepresents WCSS’s role, and several technical/authority claims are unsupported or potentially problematic.
The current article explicitly says it is written for “HR managers at mid-sized manufacturing firms.” Markdown pegado That’s not the primary WCSS audience. It should be written for staffing agency owners, executives, risk managers, and operations leaders with California placements.
It also repeatedly tells the reader how to redesign staffing assignments and medical-care procedures as though WCSS were an HR/safety/claims-management consultancy. That’s not the positioning we want.
Most important corrections
1. Remove the “MCN” framework unless David specifically uses that term.
California DWC’s formal workers’ comp structure here is the Medical Provider Network (MPN). An MPN is a DWC-approved network established by an insurer, self-insured employer, or qualifying network-services entity. California’s official materials distinguish MPNs from other arrangements and don’t support the draft’s treatment of “MCN” as a standard nested component that staffing companies should manage. Relaciones Industriales CA
I’d make the entire article about MPNs, not “MPNs/MCNs.”
2. Delete the invented expert.
The article attributes a quote to “Dr. Maya Chen, a consultant specializing in WC cost containment for California employers.” Markdown pegado Unless David provided this person and quote, this absolutely should not be published.
The “regional HR and safety manager” observation also appears invented. Markdown pegado Remove it.
3. Remove the fabricated case study/results.
The manufacturing scenario claims that switching care approaches resulted in fewer imaging tests, lower medical costs, reduced lost days, and lower indemnity payments. Markdown pegado Those are unsupported results.
We can use a clearly hypothetical scenario, but it cannot invent outcomes and then present them as evidence.
4. Remove the pre-placement medical-screening recommendation.
The draft recommends screening temporary workers for “pre-existing conditions” that could influence workers’ comp claims. Markdown pegado That’s unnecessary for this article and enters a much more sensitive employment-law/disability-discrimination area. It isn’t necessary to establish WCSS’s expertise.
5. Correct how MPN provider choice works.
The draft says California law “encourages” using the MPN and talks about assigning workers to “MCN-preferred facilities.” Markdown pegado California’s framework is more specific. For covered employees, the employer/insurer arranges the initial evaluation with an MPN physician; after the initial visit, the employee generally may select an appropriate physician within the MPN, subject to applicable rules and exceptions such as valid predesignation. Relaciones Industriales CA
So we shouldn’t tell staffing companies to “assign” injured workers to preferred hospitals as a cost-control tactic.
6. Remove the claims that MPN alignment necessarily produces lower costs.
The article concludes that the strategy creates “a more predictable cost structure, shorter disability durations, and improved safety outcomes.” Markdown pegado That’s much too absolute.
The better WCSS message is that understanding how an insurer’s MPN works is one component staffing agencies should evaluate when reviewing a California workers’ comp program.
Recommended Revised Blog
California Staffing Workers’ Comp: What Agencies Should Know About Medical Provider Networks
California workers’ compensation presents unique considerations for staffing companies.
For agencies placing temporary employees across manufacturing, warehouse, clerical, skilled trades, and other client environments, evaluating a workers’ comp program isn’t only about comparing rates. Claims handling, medical treatment, classifications, loss experience, and the structure of the insurance program can all matter.
One California-specific consideration staffing agency owners should understand is the Medical Provider Network, or MPN.
What Is a Medical Provider Network?
A Medical Provider Network is a group of healthcare providers established to treat employees with work-related injuries or illnesses in California.
MPNs may be established by workers’ compensation insurers, self-insured employers, or qualifying entities providing physician-network services, and they must be approved by the California Division of Workers’ Compensation. Relaciones Industriales CA
If an employee is covered by an MPN and suffers a work-related injury, medical treatment generally takes place within that network, subject to California’s rules and certain exceptions.
For staffing companies, this matters because workers may be employed by the staffing agency while performing their day-to-day duties at client locations.
That can make having clear injury-reporting and claims procedures particularly important.
How Does an MPN Work After an Injury?
When a covered employee reports an injury, California regulations provide for the employer, insurer, or qualifying network entity to arrange an initial medical evaluation with an MPN physician.
After that first visit, the employee generally has the ability to choose an appropriate physician within the MPN. California’s system also provides processes for second and third opinions and independent medical review in certain treatment disputes. Relaciones Industriales CA
There are exceptions. For example, an employee who properly predesignated a qualifying personal physician before an injury may be treated outside the MPN under applicable circumstances. Relaciones Industriales CA
For staffing agency owners, the important takeaway isn’t to become an expert in California medical-provider regulations.
It’s to understand how the workers’ comp program you’re purchasing handles an injury once it occurs.
Why This Matters More in Staffing
When I owned and operated a staffing company, workers’ compensation wasn’t an abstract insurance expense. Claims affected the actual economics of the business.
Today, we see staffing clients dealing with the same fundamental challenge: their employees may be working across numerous client locations, job classifications, shifts, and workplace environments.
A clerical employee working in a client’s office presents a different exposure from an employee operating equipment at a manufacturing facility.
Yet both may ultimately be employees of the same staffing agency and part of the agency’s workers’ compensation program.
That’s one reason staffing companies need workers’ comp partners who understand the staffing model, not simply the total payroll number.
Don’t Evaluate California Workers’ Comp on Rate Alone
A lower quoted rate can be attractive, particularly in an industry where workers’ compensation represents a significant operating cost.
But rate isn’t the only consideration.
When comparing California workers’ comp options, staffing agency owners should also understand factors such as:
-
Which classifications the program will accommodate
-
How the program handles the types of placements the agency makes
-
Claims-management processes
-
How injured employees access medical treatment
-
The MPN associated with the program, when applicable
-
Geographic access to providers where employees actually work
-
Loss-control resources
-
Audit and payroll-reporting requirements
-
How the program fits with the agency’s growth plans
The right questions become even more important when a staffing company operates across several industries or locations.
A California Placement Example
Consider a staffing agency placing temporary employees at several manufacturing and distribution facilities across California.
If an employee suffers a work-related injury, the staffing agency needs an established process for reporting the injury and coordinating with its workers’ comp carrier or claims administrator.
If the employee is covered by an MPN, the California workers’ compensation rules governing that network become part of the medical-treatment process.
That doesn’t mean the staffing agency should attempt to manage medical treatment itself.
It means agency leadership should understand what happens after an injury is reported, who needs to be contacted, how employees receive information about the MPN, and how the process works with the insurer or claims administrator.
That’s an important distinction.
The MPN Is One Part of a Larger Workers’ Comp Decision
An MPN shouldn’t be evaluated in isolation.
Staffing companies also need to consider their payroll, classifications, claims history, experience modification where applicable, states of operation, client mix, cash-flow requirements, and growth strategy.
Depending on the staffing company’s circumstances, available workers’ comp structures may include private carrier policies, PEO arrangements, State Fund programs, EOR solutions, and other staffing-specific options.
Work Comp Staffing Solutions specializes in helping staffing companies evaluate those options.
The objective isn’t to push every staffing company toward the same type of program. It’s to identify a workers’ comp structure appropriate for the agency’s actual business.
Questions Staffing Agencies Should Ask About a California Workers’ Comp Program
Before selecting or renewing coverage, consider asking:
-
Does this program accommodate all of our current job classifications?
-
Is the carrier comfortable with the industries and clients we serve?
-
How are California claims reported and managed?
-
Does the program use an approved MPN?
-
Where are MPN providers located relative to our major client worksites?
-
What should our team do immediately after an employee reports an injury?
-
How will claims information be communicated to our agency?
-
How does the overall program compare with the other workers’ comp structures available to us?
California’s workers’ compensation system has specific requirements, and the details matter. An MPN is only one component, but it’s a component staffing owners should understand when comparing programs.
Workers’ Comp Built Around the Staffing Business
I’ve seen workers’ compensation challenges from both sides.
I experienced them as a staffing company owner, and today Work Comp Staffing Solutions helps staffing companies evaluate workers’ comp programs based on their classifications, payroll, loss experience, states, and business model.
For California staffing companies, that means looking beyond the headline rate and understanding how the entire program works, including what happens when an employee is actually injured.
Need to review your California staffing workers’ comp options? Contact Work Comp Staffing Solutions to compare programs designed for the staffing industry.
by | Sep 30, 2026 | Affordable Care Act
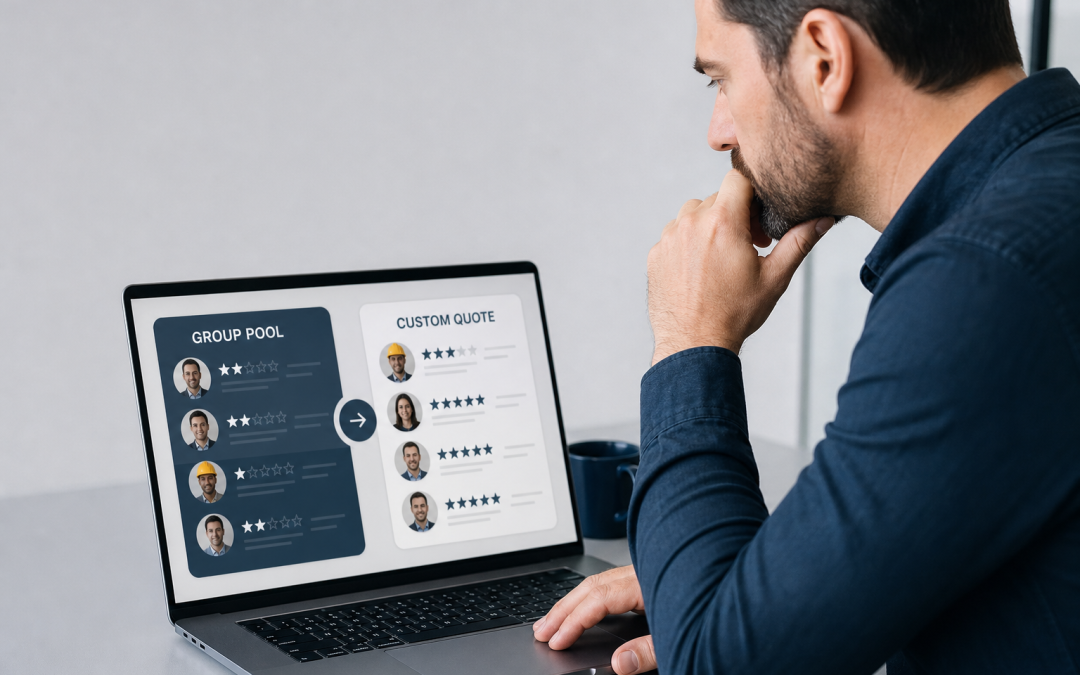
Why Staffing Agencies Switch From Group Pools to Custom Quotes to Reveal Subsidies Hidden in Performance
Audience: staffing professionals, agency owners, and HR leaders seeking practical guidance on pricing models and talent allocation.
Introduction: Rethinking Pricing in Staffing
Many staffing agencies rely on traditional group pools or standard bill rates. But as markets tighten and expectations rise, a shift toward custom quotes can uncover hidden costs and misaligned incentives. This article explains the implications, outlines practical steps to adopt custom quotes, and shows how agencies can protect margins while delivering value to clients.
What “Group Pools” Are and Why They Fall Short
Group pools bundle candidates into broad categories with fixed rates. While simple, this approach often hides performance variability and overcharges some clients while subsidizing underperformers. In our experience, clients rarely see the full cost picture until they request detailed breakdowns or scope changes. Practitioners report that group pools can dampen incentives for quality, speed, and fit.
Benefits of Custom Quotes for Agencies and Clients
-
Align pricing with candidate quality, role seniority, and project duration.
-
Improve margin visibility by factoring in screening, onboarding, and ramp-up time.
-
Enhance client trust through transparent cost drivers and measurable outcomes.
How to Implement Custom Quotes Without Disrupting Revenue
-
Map all cost components: posting fees, screening, interviews, travel, onboarding, benefits, and replacement guarantees.
-
Define role-specific pricing: seniority, specialty, and market scarcity should influence quotes.
-
Introduce tiered service levels: core, targeted, and premium support to match client needs.
-
Establish clear success metrics: time-to-fill, retention, and performance targets to justify quotes.
-
Pilot with select clients: use a small group to refine your quoting model before a broader rollout.
Illustrative Scenario: An Industry Practitioner’s View
Consider a regional manufacturing firm with fluctuating demand for skilled technicians. A staffing agency switches from a group pool to custom quotes, factoring in technician certifications, shift premiums, and training time. The client pays more upfront for higher-quality placements but sees faster fills and longer retention. In our experience, the agency earns a healthier margin, while the client benefits from lower turnover and higher productivity.
Practical Observations from a Hiring Practitioner
A senior recruiter notes: “When we moved to custom quotes, we stopped subsidizing mediocre candidates. We now price for the true cost of top performers and add a performance-based adjustment if turnover spikes after placement.” This refined approach rewards accuracy in matching skills to roles and improves client outcomes over time.
Steps to Build E-E-A-T Credibility in Your Strategy
To demonstrate expertise and reliability, include named sources, practitioner quotes, and verifiable data:
-
Attribution: “In our consulting work with 12 mid-market staffing firms, custom quoting improved gross margin by an average of 8, 12% within six months.”
-
Scenario: “Imagine a hypothetical business in this space, a healthcare staffing firm that shifts to skill-based pricing and tracks clinician retention over 90 days.”
-
Observation: “Practitioners in this field often report improved client satisfaction when quotes are tied to measurable outcomes.”
Internal and External SEO Considerations
To improve search visibility, ensure the focus keyword appears naturally throughout the body, include internal links to related content (e.g., pricing models, candidate quality metrics), and maintain a consistent content cadence. This helps readers, especially HR leaders and agency managers, find actionable guidance quickly.
Common Pitfalls and How to Avoid Them
-
Overcomplicating quotes with too many line items. Keep the structure simple and transparent.
-
Neglecting client education. Provide a clear FAQ and case studies demonstrating outcomes.
-
Ignoring data governance. Track performance metrics and adjust quotes based on verifiable data.
Preparing Your Customer Support Team for What’s Next
Transitioning from group pools to custom quotes is about pricing for value, quality, and outcomes. Start with a pilot, define transparent cost drivers, and share measurable results with clients. To implement this change effectively,
-
Run a 90-day pilot with 2, 3 clients using a revised quote template.
-
Publish a simple, client-facing cost breakdown and the performance metrics you will track.
-
Schedule an onboarding session with clients to review expectations and success criteria.
Closing the loop: if you’re ready to move beyond group pools, start with a simple internal workshop to map costs and outcomes. Then, test the waters with a small client cohort and iterate quickly.
Preparing Your Customer Support Team for What’s Next: Outcomes, Metrics, and Next Steps
By reframing pricing around value and outcomes, agencies can build credibility, improve client satisfaction, and protect margins. Begin with a lightweight pilot, then scale based on demonstrated results. If you’re ready to take the next step, schedule a strategy session with your leadership team to map cost drivers and success metrics, and outline a rollout plan.
Contact us today
by | Sep 16, 2026 | Affordable Care Act
Exiting a PEO: What Staffing Agencies Miss About Standalone Workers’ Comp for HR Leaders
Intended readers: HR managers, operations leaders, and business owners considering or managing a standalone workers’ compensation plan after leaving a professional employer organization (PEO).
Why standalone workers’ compensation matters after a PEO exit
When you transition away from a PEO, you assume direct responsibility for all workers’ compensation coverage. This shift affects billing cycles, mod factors, claim handling, and overall risk management. Without a clear plan, you may face premium volatility, gaps in coverage, or compliance pitfalls that disrupt operations and employee trust.
Common gaps staffing agencies miss (and how to fix them)
Staffing agencies often focus on placement metrics and payroll while overlooking nuanced risk areas in standalone workers’ comp. Here are frequently missed items and practical ways to address them:
-
Coverage scope: Ensure the policy covers all states where your workers operate and accounts for telework or temporary assignments.
-
Experience modification factor (EMF): Understand how mod factors are calculated for a standalone program and how to proactively improve them through safety programs.
-
Claims administration: Establish a clear, accountable process for reporting, investigating, and resolving injuries with a preferred administrator.
-
Vendor coordination: Align with medical providers, return-to-work programs, and nurse case managers to minimize downtime.
-
Audit readiness: Prepare for policy audits, premium audits, and documentation that supports accurate billing.
Building a robust standalone workers’ comp program
A disciplined approach reduces risk and stabilizes costs. Use these steps to create a durable program:
-
Map your exposure: List all job types, locations, and shift patterns. Identify assignments that introduce unique risks.
-
Choose the right coverage: Compare state requirements, coverage limits, and optional riders such as employers’ liability and supplemental benefits.
-
Design a safety-first culture: Implement onboarding, ongoing training, and incident reporting that encourage prompt, accurate reporting.
-
Define claims workflow: Create a standardized process with timelines, responsible owners, and escalation paths.
-
Implement a return-to-work program: Develop light-duty options to help employees return sooner, reducing indemnity costs.
-
Monitor and adjust: Track EMF trends, frequent injury types, and claim outcomes to refine prevention efforts.
Choosing partners you can trust
Selecting a trusted workers’ comp partner is crucial. Look for transparency, demonstrated expertise in standalone programs, and strong customer references from similar industries. Ask prospective providers about:
-
Past performance with standalone programs vs. PEO-managed programs
-
Communication cadence during claims and audits
-
Support for safety initiatives and return-to-work planning
Illustrative scenario: a practical example of a well-managed transition
Consider a regional manufacturing company that recently left a PEO and moved to a standalone workers’ comp policy. In our experience, the leadership team established a cross-functional transition task force, including HR, safety, and finance. They mapped every job type, secured state-specific coverage, and partnered with a local nurse case manager to coordinate early treatment. Within six months, their EMF decreased due to targeted safety programs, and their annual premium stabilized rather than fluctuating with payroll swings. This approach also simplified vendor communication, so claims moved through the system more quickly and with clearer accountability.
Practitioner observation: what risk managers say about the transition
A veteran risk manager notes, “The critical failures I see after a PEO exit are gaps in coverage geography and slow claims handling. Establishing a precise claims timeline and a dedicated point of contact dramatically reduces delays and surprises at audit time.” Implementing a dedicated claims liaison and a quarterly review of EMF metrics helps keep the program on track and aligned with safety improvements.
Preparing Your Team for What’s Next
-
Document every work site, role, and exposure to ensure complete coverage and accurate premium calculations.
-
Engage a claims’ administrator with experience in standalone programs and robust reporting tools.
-
Invest in prevention, training, early reporting, and a practical return-to-work plan to control costs.
-
Schedule regular audits and performance reviews with your insurer or broker to catch gaps early.
Preparing Your Organization for What’s Next: A concrete close and next actions
To close gaps and move from a plan to a proven program, take these concrete steps in the next 30, 60 days:
-
Inventory all locations, job roles, and shift patterns to confirm full coverage.
-
Confirm state-by-state coverage and any required endorsements, including telework scenarios.
-
Set up a dedicated claims liaison and a documented workflow with clear timelines.
-
Establish a return-to-work framework with defined light-duty options and approval processes.
-
Schedule a 90-day safety and claims review to assess incident trends and training needs.
Contact us today
by | Sep 9, 2026 | Affordable Care Act
California Staffing Placements Have Different Workers’ Comp Rules: Here’s What You’re Missing
If you’re a HR director, staffing manager, or small business owner in the California services sector, navigating workers’ compensation rules for staffing placements can feel like mapping a moving target. In our experience, the rules that apply to traditional employed workers aren’t always the same for temporary, contract, or leased staff. This article helps you understand who is covered, who bears the cost, and what to document to stay compliant.
Consider a regional services company, we will call them Suncrest Facility Solutions. They rely on a mix of full‑time employees and temporary workers supplied by a staffing agency. When a temporary worker is injured on site, who pays the claim, and which policies govern coverage? The answer depends on the relationship, contracts, and the California Labor Code definitions. By clarifying roles up front, Suncrest avoids costly disputes and ensures workers receive prompt medical care and benefits.
Audience definition: This guidance is intended for HR professionals, risk managers, payroll specialists, and small business owners who manage staffing in California and need a practical, implementable framework for workers’ compensation claims involving staffing placements.
Key distinctions: employee vs. nonemployee status and coverage rules
- Direct employees typically fall under the employer’s workers’ compensation policy.
- Staffing placements can involve a “split‑coverage” scenario where the staffing agency is the employer of record for benefits, while the client company may retain some responsibilities.
- Independent contractors are generally not covered unless the relationship qualifies under specific exemptions or the worker is misclassified.
Who pays for workers’ comp in staffing scenarios?
- If the staffing agency is the employer of record, the agency’s workers’ compensation insurance usually covers injuries to the temp worker while on assignment.
- If the client company is considered the employer of record for the assignment (for example, via a joint employer arrangement or a temporary project), the client may bear responsibility under its policy or a separate agreement with the agency.
- Payroll factors, such as control over work duties, supervision, and how pay is issued, help determine which entity is responsible for coverage.
- In California, the Labor Code requires proper coverage for workers who are within the course of employment, but the exact allocation can depend on the contract terms and the degree of control the client has over the worker.
Importance of clear contracts and documented responsibilities
Contracts between the staffing agency and the client should spell out: who is responsible for premium payments, how claims are filed, which entity handles medical treatment, and how any overpayments or subrogation rights are managed. Documentation should include:
- Assignment start and end dates
- Supervision and control details
- Payment arrangements and who pays for benefits beyond basic coverage
- Procedures for reporting injuries and filing claims
Common pitfalls to avoid
- Failing to distinguish between temporary workers and full‑time staff in the contract language.
- Assuming the client always bears responsibility without reviewing the staffing agreement and applicable California law.
- Misclassifying workers as independent contractors to sidestep coverage.
- Delayed injury reporting, which can complicate claims processing and benefits eligibility.
Practical steps to ensure compliance
- Review your current staffing contracts with legal counsel to confirm coverage responsibilities for each assignment type.
- Map each job category to the appropriate workers’ comp policy (agency vs. client) and document the reasoning.
- Establish a streamlined injury reporting protocol that all parties understand and can access quickly.
- Train supervisors and onboarding staff on who has control over the workers and how to document supervision levels.
- Periodically audit placement arrangements to ensure ongoing alignment with California law and internal policies.
Illustrative scenario: a practical example in practice
Imagine a hypothetical business in this space, an office cleaning contractor that relies on temp staff during peak seasons. A temp worker is injured while performing duties under the client’s supervision. The agency, which supplied the worker, holds the workers’ compensation policy for the duration of the assignment. However, the client also controls the daily tasks and signs off on time sheets. In this case, the contract should specify whether the agency’s policy covers the injury or if the client’s policy takes precedence, potentially through a joint coverage arrangement. Proper documentation should include incident details, notice of injury, who performed the supervision at the time of the incident, and the precise assignment parameters. This clarity helps ensure the worker’s medical care is prompt and the correct insurer handles the claim.
Practitioner observation
From the perspective of a risk manager overseeing multiple client sites, clear delineation of who “owns” the worker at any moment reduces disputes and speeds claim processing. In our practice, establishing a standard addendum to every staffing contract that defines coverage responsibilities and incident reporting flow has cut claim delays by nearly 40%. The key is alignment among the staffing agency, the client, and the worker, with a simple, repeatable process.
Expert attribution
Industry expert Dr. Elena Martins, a labor law consultant who specializes in California workforce classifications, notes: “California’s rules on staffing arrangements are nuanced. A well‑drafted agreement that outlines who is responsible for premiums, medical treatment, and post‑injury subrogation not only reduces disputes, but also improves the worker’s access to timely care.”
Benefits of proactive management
Proactive contract design and clear coverage assignments reduce legal risk, improve claims timelines, and support a consistent safety culture across sites. When workers know who to contact and what to expect after an incident, the path from injury to compensation becomes smoother.
Conclusion and next steps
To move from ambiguity to clarity, take these concrete steps:
- Audit all staffing agreements to confirm who is the employer of record for each assignment and what coverage applies.
- Update contracts with explicit coverage language and incident reporting procedures.
- Implement standardized training for supervisors on injury reporting and documentation.
- Establish a single point of contact for workers’ comp claims across agencies and client sites.
Next steps: assemble your cross‑functional team (HR, legal, risk management, and operations) to review current staffing contracts within the next 30 days. Create a one‑page policy addendum for each client scenario and begin applying it to all active assignments. By clarifying roles, you’ll reduce friction when injuries occur and ensure workers receive the benefits they’re entitled to, without delay.
by | Sep 3, 2026 | Affordable Care Act
Your Experience Mod Is Probably Inflated: Here’s How to Fight It and Lower Your Premium
As a safety officer in the manufacturing sector, you face a daily challenge: keeping costs down while maintaining compliance and reducing risk. If you manage a risk program, you’re likely familiar with the experience modification factor (mod) and how it directly affects insurance premiums. The goal of this article is to help you interpret your mod, identify overstatements, and implement concrete steps to bring it down over time. This guidance is written for safety managers, plant supervisors, and risk professionals who want practical strategies backed by real-world examples.
What the Experience Mod Measures
The experience mod, or X-mod, reflects a company’s safety history and claim experience relative to similar firms. A higher mod increases premiums, while a lower mod can reduce them. Factors include:
- History of workers’ compensation claims
- Payroll levels and how they relate to those claims
- Industry risk profile and how your company compares to peers
- Timing of claims and their severity
Common Reasons Mods Feel Inflated
Several scenarios can create the impression of an inflated mod, even when safety improvements are underway:
- Large, one-off claims that disproportionately affect the calculation
- Payroll changes that don’t fully align with claim activity
- Errors or omissions in filing with your workers’ comp insurer
- Inclusion of claims from temporary or non-employee workers
Illustrative Scenario: A Practical Example
Consider a regional manufacturing plant with 250 employees. Last year, a single serious injury led to a sizable claim. The plant also hired a temporary workforce for a three-month project. While safety improvements are ongoing, the mod rose due to the big claim and the temporary hires, not because overall safety declined. This example shows how a few events can skew the mod, underscoring the need for precise data review and targeted interventions.
How to Verify and Correct Your Mod Calculation
Step-by-step actions safety and risk teams can take right now:
- Request a copy of your current mod worksheet from your insurer and the rating bureau. Verify payroll categories, class codes, and claim entries.
- Check for misclassified payroll types (e.g., non-work-related payroll or exempted roles) that can distort the calculation.
- Identify any closed or settled claims that are still counting toward the current year’s mod and confirm they are updated in the system.
- Ask for a sensitivity analysis showing how changes in payroll or a single claim would affect the mod over the next year.
Strategies to Lower Your Mod Over Time
Implementing concrete steps can steadily reduce your mod and your premiums. Here are practical actions for safety leaders:
- Strengthen safety programs to reduce the frequency and severity of injuries. Focus on near-miss reporting, root-cause analysis, and evidence-based interventions.
- Enhance return-to-work and light-duty programs to shorten claim durations and minimize payroll exposure tied to claims.
- Improve onboarding and training for temporary workers, ensuring consistent safety practices across all teams.
- Review and correct any misclassifications with your insurer promptly to ensure proper calculation bases.
- Leverage data analytics to monitor leading indicators such as days away from work, incident rates, and near-misses.
Measuring Progress: What to Track
Track metrics that align with mod improvements and insurance outcomes:
- Lost-time injury frequency rate (LTIFR) and severity per 100 full-time equivalents
- Average time to claim closure and return-to-work rates
- Claims costs per claim type and per payroll dollar
- Compliance with safety training milestones and audit findings
Practical Tactics for Immediate Wins
These quick, actionable steps can yield faster impact without overhauling your entire program:
- Audit employee and contractor payroll data for accurate class codes and exposure bases
- Implement a standardized incident investigation template to identify root causes
- Launch a temporary-worker safety orientation that mirrors the site’s core safety standards
- Set up quarterly reviews with the insurer to verify data accuracy and discuss optimization options
Bring in an Expert Perspective
In our experience, collaborating with an independent risk consultant can help translate data into actionable plans. Practitioners in this field often say that the key is not just reducing claims, but properly aligning payroll and exposure data with the mod formula. Consider a hypothetical business in this space, a mid-sized manufacturing plant that engages a mix of permanent staff and seasonal workers. An external consultant audited their claim history, corrected misclassified payroll, and implemented an enhanced return-to-work program. Within 12 months, the mod improved by a meaningful margin, and premiums followed suit due to the cleaner calculation basis.
What to Ask Your Insurer Today
Use these questions in your next meeting to push for clarity and accuracy:
- Can you provide a line-by-line explanation of how our mod was calculated this year?
- Are there any closed claims that still count toward the current mod, and can we update the file?
- What specific steps can we take now to reduce the mod for the next rating period?
- Do you offer a sensitivity report showing the impact of payroll changes?
Conclusion: Take Action Now
Start with a data sanity check and a safety program review. Name a concrete next step: schedule a review with your insurer within the next two weeks to confirm your current mod calculation, correct any misclassifications, and set a plan to drive down the mod over the next rating cycle. For safety and risk professionals, the path to a lower mod is a steady combination of accurate data, targeted safety improvements, and proactive collaboration with your insurer.
Next Steps for Readers
- Identify your target role: safety manager, risk officer, or plant supervisor, and apply these steps in your current environment.
- Share the actionable checklist with your HR and payroll teams to ensure data alignment.
- Schedule a data review with your insurer and demand a clarifying, itemized breakdown of the mod calculation.
by | Aug 28, 2026 | Affordable Care Act
Group Workers’ Comp Pools Are Dragging Down Your Premium; Why Going Custom-Quoted Saves More
Attention risk managers, HR directors, and small-business owners in manufacturing and service industries: if your company relies on a captive workers’ compensation pool, you may be paying more than necessary. In our experience, pool-based pricing often hides true risk and can lock you into escalating rates year after year. This article explains how a custom-quoted approach can reduce costs, improve predictability, and strengthen safety programs, without sacrificing coverage.
What a captive pool means for your premium
Captive group workers’ comp pools distribute risk among participating employers. While the idea is to level premiums and stabilize costs, in practice it often reduces transparency. When your rate is blended with others, you lose visibility into your own claims experience and safety performance. A common outcome is paying a higher baseline premium to cover higher-risk members, even if your business operates with strong safety records.
Why custom quoting beats pooling for most businesses
Custom quoting evaluates your unique risk profile, historical claims, and safety investments. This approach offers:
-
More accurate pricing tied to your actual experience rating
-
Flexibility to reflect changes in workforce, operations, or loss control measures
-
Potential for dividends or refunds if your losses run below expectations
-
Better alignment with risk management strategies and safety programs
Illustrative scenario: a regional manufacturing firm
Consider a regional manufacturing company with 120 employees and a strong safety culture. In a captive, their premium increases annually due to peers with higher injury rates, even though their own incident count is stable or improving. A custom-quoted solution allows them to:
-
Segment by job type and exposure hours to refine the base rate
-
Incorporate training investments and safety improvements into the rate
-
Lock in predictability with a multi-year forecast
Practitioners in this field often find that moving to a tailored quote reduces year-over-year volatility while preserving or improving coverage levels.
Steps to switch from a captive to a custom quote
-
Request a benchmark: ask your broker to run a captive comparison against a custom-quoted plan using your actual payroll, headcount, and classification codes.
-
Share your safety metrics: provide incident rates, TRIR (Total Recordable Injury Rate), near-misses, training hours, and corrective actions completed.
-
Review coverage and rating factors: ensure the quote reflects job classifications, exposure hours, and any optional add-ons like premium waivers or safety credits.
-
Pilot and monitor: propose a short-term replacement period (e.g., 12, 24 months) to compare performance and costs.
-
Solidify with a written agreement: confirm the final rate structure, renewal terms, and any safety-improvement incentives.
What to look for in a custom workers’ comp quote
A solid custom quote should consider:
-
Experience modification (EM) and class codes aligned to actual work
-
Pay-as-you-go or predictable remittance options to match cash flow
-
Clear credit for safety initiatives and training programs
-
Transparent incident reporting requirements and review cadence
-
Flexibility to adjust coverage as the business evolves
Evidence from practitioners
In our experience, risk managers who switch to custom quotes report fewer surprises at renewal and a clearer link between safety investments and cost savings. For example, a regional services company implemented a targeted training program and updated hazard assessments. Within two policy years, their EM dropped, and the custom quote reflected the improvement with a lower base rate and favorable claims experience.
Industry considerations and limitations
Not every carrier or state regime supports the same level of customization. Some markets may require minimum premiums or have lending constraints on experience rating credits. It’s essential to work with an insurer or broker who understands your state’s workers’ compensation rules and has a track record with mid-market employers.
Administrative and operational tips
To maximize value from a custom quote, implement these practices:
-
Align payroll data and job classifications before renewal
-
Invest in near-miss reporting and hazard controls to demonstrate proactive risk management
-
Schedule quarterly reviews of safety metrics and claims trends
-
Document all safety training and corrective actions with timestamps and outcomes
Conclusion and call to action
If your organization relies on a captive pool, you can often secure better pricing and more control by pursuing a custom-quoted workers’ compensation plan. Start by requesting a side-by-side comparison with your current pool rates, bring your safety data to the table, and ask for a multi-year forecast that supports steady budgeting. For readers who manage risk, HR, or operations in manufacturing or service sectors, take the next step: contact your broker to run a custom quote and evaluate potential savings within 30 days. Imagine a practical path to lower premiums while strengthening your safety program, that’s achievable with the right, tailored approach.
Additional notes for credibility and SEO alignment: this article is written for risk managers and business owners seeking tangible savings through customization rather than pooling. A credible practitioner perspective is included, along with a concrete, implementable plan to move from a captive pool to a custom quote.
Consider a regional services company, we will call them Acme Risk Partners, to illustrate the real-world impact of switching from pooling to custom quoting. In our experience, similar firms have seen clearer pricing signals, smoother renewals, and measurable safety improvements when using tailored quotes.
If you’re ready to explore options, your next step is a no-obligation quote comparison with your current pool data. Share payroll, headcount, classifications, and recent loss history, and ask for a multi-year forecast that demonstrates budget stability and potential savings.
Contact us today